Author: admin-su

  • ¿Cómo funciona realmente el sistema de farmacias en España?

    Farmacia en España

    ¿Cómo funciona el sistema de farmacias en España? La respuesta es sencilla: te vas a encontrar con un modelo de proximidad muy distinto al de otros países. Aquí, la farmacia no es solo un sitio donde compras medicamentos; es un centro de salud comunitario con una regulación estricta para asegurar que siempre tengas ayuda cerca de casa.

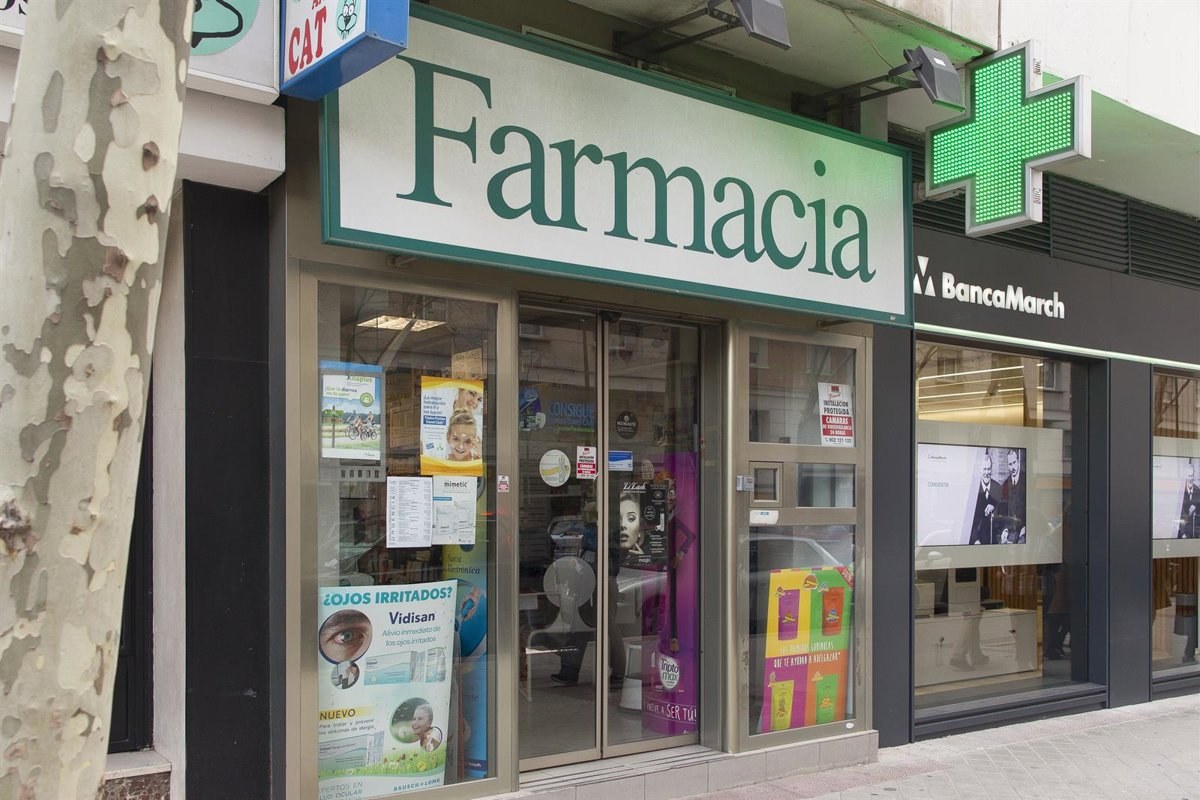
    Si caminas por cualquier barrio de Madrid, Barcelona o un pueblo perdido en la sierra, verás ese letrero de la cruz verde iluminada. Esa cruz no es solo decoración. Es la señal de que ahí hay un profesional sanitario que puede orientarte sin que tengas que ir a las urgencias de un hospital.

    Lo primero que hay que entender es que la farmacia es un establecimiento sanitario, no una tienda cualquiera. No puedes ir a cualquier lado a comprar antibióticos o fármacos con receta; ese es un privilegio exclusivo de estos locales. Esa distinción es la que mantiene el orden en el sistema de salud español.

    Es un sistema híbrido. Por un lado, está la parte de la dispensación de medicamentos recetados por el médico, que suele estar subvencionada por el Estado. Por otro, tienes el consejo farmacéutico y la venta de productos de parafarmacia, cosmética o suplementos, donde el farmacéutico actúa más como un asesor de bienestar personal.

    El papel del farmacéutico como primer filtro sanitario

    Seguramente alguna vez te has despertado con una tos persistente o un malestar estomacal y te has preguntado si deberías ir al médico o si puedes resolverlo en la esquina. En España, el farmacéutico es ese primer filtro. Su labor va mucho más allá de entregarte una caja de pastillas y cobrarte.

    El farmacéutico tiene la formación para evaluar qué tan graves son tus síntomas. Si le explicas que te duele el pecho o que tienes una fiebre que no baja, te dirá claramente que te dirijas a un centro de salud. Ese triaje informal es lo que hace que el sistema sea eficiente y evita que las guardias hospitalarias colapsen por problemas menores.

    No se trata solo de dar consejos, sino de garantizar la seguridad. El profesional revisa que no haya interacciones peligrosas entre lo que ya estás tomando y lo que te acaba de recetar tu doctor. Es un trabajo de vigilancia constante que ocurre en el mostrador, de forma rápida pero muy meticulosa.

    Imagina que vas con una duda sobre un suplemento de magnesio que viste en una revista. El farmacéutico no solo te vende el bote; te explicará si realmente lo necesitas o si quizás tu alimentación ya cubre esa carencia. Es una consulta de salud rápida, sin cita previa y sin la frialdad de un hospital. Es un trato humano y directo.

    Esta cercanía genera una confianza que no se ve en otros modelos de distribución. El farmacéctor de tu barrio te conoce; sabe si eres un paciente crónico o si sueles comprar siempre lo mismo para tus hijos. Esa relación es el núcleo de la atención sanitaria en la calle.

    Diferencias entre recetas oficiales y productos de venta libre

    Aquí es donde la gente suele confundirse. Es fundamental que distingas entre lo que el médico te ha prescrito y lo que puedes comprar por tu cuenta. La distinción es clara y está regulada por la ley de salud de cada comunidad autónoma.

    Cuando tienes una receta electrónica, el proceso es casi automático. El farmacéutico escanea tu tarjeta sanitaria, el sistema se conecta con la base de datos de la seguridad social y el medicamento aparece en su pantalla. En ese caso, gran parte del coste lo cubre el Estado y tú solo pagas una pequeña parte según tu renta o tu condición de paciente.

    Si decides comprar algo por tu cuenta, como un analgésico para un dolor de cabeza ocasional, la dinámica cambia. En ese caso, el producto es de venta libre y pagas el precio completo de mercado. Es una transacción comercial estándar, pero el consejo profesional sigue siendo gratuito y obligatorio.

    Tipo de Producto Requiere Receta Quién Paga la Mayoría Uso Principal
    Medicamento con receta Sí El Estado / Seguridad Social Tratamientos médicos específicos
    Medicamento de venta libre No Tú (el consumidor) Síntomas leves y puntuales
    Parafarmacia y cosmética No Tú (el consumidor) Cuidado personal y bienestar

    Es interesante cómo la sección de parafarmacia ha crecido tanto. Ahora, si entras en una farmacia de una zona comercial, te encuentras con estanterías que parecen de una tienda de belleza de alta gama. Hay cremas, protectores solares, champús especializados y productos de higiene que antes eran difíciles de encontrar en un entorno clínico.

    Sin embargo, aunque parezca una tienda de cosmética, la esencia es la misma. Si vas a la farmaciavirgendelcamino.com o a cualquier otra de tu ciudad, la prioridad es la salud. La cosmética es el complemento, pero el núcleo es la medicina. Esa dualidad hace que la farmacia sea un negocio rentable, pero también conlleva una responsabilidad social enorme.

    A veces, la gente intenta buscar estos productos en grandes superficies o supermercados para ahorrar un poco. Pero la diferencia es el asesoramiento. Un supermercado te vende el bote; el farmacéutico te explica cómo aplicarlo y por qué es mejor para tu tipo de piel.

    La logística detrás del mostrador: el stock y la trazabilidad

    ¿Alguna vez te has preguntado cómo es que siempre tienen lo que necesitas, incluso si es un medicamento muy específico? La logística de las farmacias españolas es una maquinaria de precisión. No es que tengan todos los medicamentos del mundo acumulados en el almacén, porque eso sería un gasto inasumible.

    Existe un sistema de distribución muy ágil. Los laboratorios envían los pedidos a los almacenes mayoristas y estos los reparten a las farmacias varias veces al día. Si vas a una farmacia y no tienen una caja de un antibiótico concreto, es muy probable que te digan que lo tienen listo en un par de horas o que lo pidan para el día siguiente sin coste adicional.

    Esta gestión es clave para la seguridad. Cada caja de medicamento tiene un número de lote y una fecha de caducidad que se controla estrictamente. Si hay un problema con un lote específico, la farmacia puede identificarlo rápidamente gracias a la digitalización de sus pedidos. Es un control de trazabilidad total que te da tranquilidad.

    Para entender la complejidad, piensa en un paciente que necesita un tratamiento para la hipertensión. Ese medicamento debe estar siempre disponible; no puede faltar. La gestión de la farmacia implica un equilibrio constante entre tener lo necesario para cubrir la demanda y no tener exceso de productos que caduquen en el estante. Es una ciencia de gestión aplicada a la salud.

    Además, la digitalización ha cambiado las reglas. Antes, el farmacéutico tenía que anotar todo en libros de papel. Ahora, todo está conectado con los sistemas de salud. Esto permite que la atención sea más rápida y que los errores humanos se reduzcan al mínimo. La tecnología es la aliada silenciosa de la atención farmacéutica.

    El fenómeno de la parafarmacia y el bienestar moderno

    No podemos ignorar cómo ha cambiado el comportamiento del consumidor en los últimos años. La gente ya no va a la farmacia solo cuando está enferma. Ahora vamos cuando queremos cuidarnos, cuando queremos mejorar la dieta o cuando queremos probar un nuevo ritual de cuidado de la piel.

    Este auge de la parafarmacia ha transformado el diseño de los locales. Ya no son lugares que huelen solo a desinfectante y tienen luces blancas frías. Muchos locales ahora tienen un aire mucho más acogedor, con estanterías de madera y zonas de prueba para productos de belleza. Es una tendencia que busca que el paciente se sienta cómodo, no intimidado.

    Sin embargo, esto plantea un debate. ¿Se está perdiendo la esencia de la farmacia al parecerse tanto a una tienda de belleza? Algunos profesionales defienden que esta diversificación es necesaria para que la farmacia siga siendo un negocio viable frente a la competencia de las grandes plataformas de venta online. Es una cuestión de supervivencia económica.

    El reto es mantener el equilibrio. El cliente puede querer un sérum facial de lujo, pero el farmacéutico debe seguir siendo el experto que te advierta si ese sérum puede interactuar con la crema que usas para una dermatitis. La venta de productos de bienestar debe ir siempre de la mano con el criterio clínico. No es solo vender, es saber qué se está vendiendo.

    La competencia de las ventas online es feroz. Es cierto, es mucho más barato comprar un bote de vitaminas en una web que en la farmacia de la esquina. Pero la web no te mira a los ojos cuando le dices que te sientes mal. La web no te pregunta si estás tomando otros medicamentos. Esa ventaja competitiva de la atención presencial es lo que mantiene viva la farmacia tradicional.

    Al final, lo que el cliente busca es confianza. Puedes comprar un producto online por ahorrarte un par de euros, pero si el producto no es lo que necesitabas, el proceso de devolución o la falta de información te pueden salir más caros. La farmacia ofrece la seguridad de la respuesta inmediata.

    Incluso en los casos de productos naturales o fitoterapia, la presencia del profesional es vital. No es lo mismo tomar una hierba para dormir que tomar un suplemento con una indicación médica clara. El conocimiento especializado es el valor añadido que nadie puede copiar con un algoritmo.

    Es verdad que las grandes plataformas online son más baratas, pero ninguna te va a explicar qué hacer si el medicamento te sienta mal.

    Preguntas frecuentes

    ¿Cómo puedo identificar una farmacia de guardia en España?

    Puedes consultar los horarios de guardia en el escaparate de cualquier farmacia o a través de la aplicación de salud de tu comunidad autónoma.

    ¿Es necesario presentar receta médica para comprar medicamentos en España?

    Sí, los medicamentos con receta (antibióticos, psicótropos, etc.) requieren prescripción médica, mientras que los de venta libre no.

    ¿Qué documentos necesito para comprar medicamentos con receta?

    Debes presentar la receta médica (física o electrónica) y tu tarjeta sanitaria de la seguridad social o el seguro privado.

    ¿Qué diferencia hay entre una farmacia y un parafarmacia en España?

    Las farmacias venden medicamentos, mientras que las parafarmacias solo ofrecen productos de higiene, cosmética y nutrición sin capacidad de dispensar fármacos.

    ¿Pueden las farmacias en España vender medicamentos online?

    Sí, pero solo las farmacias físicas con licencia oficial pueden realizar la venta de medicamentos a través de sitios web autorizados.
  • The Realities of Navigating Personal Loans in California

    Finding the best personal loan in California depends entirely on whether you are trying to fix a credit score, consolidate a mountain of debt, or simply need a quick infusion of cash for an unexpected emergency.

    You aren’t going to find a single “best” option because the market is split between aggressive fintech lenders and traditional credit unions. Your choice depends on your credit score, how much you need, and how fast you need it. If you walk into a branch with a 600 credit score, don’t expect the same terms a tech worker in Palo Alto gets.

    California is a massive market. Whether you are living in San Diego or navigating the high costs of San Mateo County, the math stays roughly the same. You are trading a piece of your future income for liquidity today. It is a simple transaction, but the fine print is where people lose their shirts.

    Before you sign anything, you need to know exactly what kind of borrower you are. Are you a “prime” borrower with a score above 740, or are you someone just trying to keep your head above water? That distinction changes everything from your interest rate to whether a lender will even look at your application.

    Decoding the Numbers and Interest Rates

    Interest rates are the only thing that truly matters when you look at the long-term cost of a loan. A lower rate sounds great on a brochure, but the APR (Annual Percentage Rate) is the number that actually tells you the truth. It includes the interest plus any sneaky fees they’ve tucked away in the fine print.

    Credit unions often provide better rates than big banks because they are member-owned. For example, Cal Coast is here to lend you the money you need at a lower rate, with rates starting as low as 12.88% APR. They offer loans up to $30,000 with terms reaching up to 60 months, and importantly, they don’t charge a prepayment penalty. If you get a bonus and want to kill the debt early, you can. That is a massive advantage.

    If you need more substantial capital, other institutions might be more appropriate. Some lenders offer unsecured loans, meaning you don’t have to put your car or house on the line as collateral, ranging from a $2,500 minimum up to $100,000. You get fixed rates and a variety of terms to play with, but you’ll likely need a stellar credit profile to hit those higher amounts.

    It’s a trade-off. You can get more money, but the price per dollar borrowed goes up. If you are looking at a $30,000 personal loan, you need to calculate your monthly payment carefully. A high interest rate on a large sum can turn a “helpful” loan into a financial anchor. Do the math before you commit.

    Comparing Loan Structures

    You generally have two ways to access cash: a lump sum or a line of credit. A personal loan gives you all the money at once. You get it, you spend it, and you start paying it back. It is straightforward. It is predictable.

    A personal line of credit is different. It works more like a credit card. You are approved for a certain amount, but you only take what you need, when you need it. You only pay interest on the money you actually draw. It is more flexible, but it requires more discipline to manage effectively.

    If you’re looking for a way to handle a specific expense, like a home repair, the lump sum is usually better. If you want a safety net for a series of small repairs, the line of credit wins. Choose your weapon wisely.

    The Credit Score Spectrum

    Your credit score is the gatekeeper. If it is high, you have the luxury of choice. If it is low, you have the necessity of survival. Many people in California find themselves in the latter category, often due to high utilization or a single missed payment during a rough patch. If that describes you, don’t panic, but do be realistic about your options.

    The lenders who specialize in “bad credit” are often online-based fintech companies. They use different algorithms to look at your utility payments or your employment history rather than just your FICO score. If you are looking for the best bad credit personal loans in California, you might find success with companies like Upstart, OneMain Financial, Prosper, or even the San Diego County Credit Union. These lenders are often more willing to take a risk on someone who is rebuilding.

    However, these loans come with a caveat. The interest rates will be significantly higher than what a prime borrower receives. You are essentially paying a premium for the privilege of being given a chance. It is a tool for stabilization, not for long-term wealth building. Use it to fix your situation, not to fund a lifestyle you can’t afford. (I have seen too many people use high-interest debt to buy things that depreciate instantly.)

    When you apply for these loans, keep your expectations managed. You might get approved, but the monthly payment might be a tight squeeze. Always check for “origination fees.” These are one-time costs taken off the top of your loan. If you borrow $5,000 but they charge a 5% origination fee, you only see $4,750 in your bank account, but you owe interest on the full $5,000.

    It is a sneaky way to borrow. Always look at the total cost of the loan over its entire life. A low monthly payment on a 72-month loan might look easy, but you could end up paying back double what you originally borrowed.

    Strategies for Debt Consolidation

    Debt consolidation is perhaps the most common reason people seek out personal loans. If you have five different credit card balances, each with a 24% interest rate, you are bleeding money. It is much more efficient to roll those balances into one single loan with a much lower rate. This simplifies your life and your bank account.

    In San Mateo County, for instance, Monterra Personal Loans can be helpful if you are looking to consolidate debt, offering rates as low as 9.74% APR for amounts up to $35,000. That is a significant drop from credit card rates. By moving the debt to a fixed-rate installment loan, you create a clear endpoint. You know exactly when you will be debt-free.

    But consolidation is not a magic wand. It is a mathematical maneuver. It only works if you stop using the credit cards you just paid off. If you consolidate your $10,000 in credit card debt into a personal loan, and then you run your credit cards back up to their limits, you have effectively doubled your debt. You have moved the problem, not solved it.

    To make consolidation work, you need a plan. You need to treat the new loan as a final settlement of your past mistakes. If you don’t change the spending habits that led to the debt in the first place, you are just spinning your wheels. The loan is the tool; you are the operator. The tool won’t work if you don’t know how to use it.

    It’s a fresh start. Use it wisely.

    Lender Type Best For… Typical Interest Rates
    Credit Unions Prime borrowers, low rates Low (e.g., 12.88% APR)
    Traditional Banks Established customers Moderate
    Fintech/Online Speed and bad credit High
    Specialty Lenders Debt consolidation Variable

    Practical Steps for Getting Approved

    Before you hit the “apply” button, you need to clean up your house. Even if you aren’t a perfect borrower, you can present the best possible version of yourself to a lender. This means checking your credit report for errors. If there is a mistake on your report, it could be costing you thousands of dollars in interest. Fix it before you apply.

    Gather your documentation. You will need proof of income, usually your last two pay stubs or a W-2. You’ll also need identification and a list of your monthly expenses. Lenders want to know that you have a “debt-to-income” ratio that makes sense. If your monthly debt payments already take up 45% of your income, most lenders are going to say no, regardless of how nice your credit score is.

    You should also consider the timing. Don’t apply for a personal loan at the same time you are applying for a mortgage or an auto loan. Every time you apply for credit, it triggers a “hard inquiry” on your credit report, which can cause a small, temporary dip in your score. If you are planning on a big life change in the next six months, wait. If you need the money now, just be prepared for that slight dip.

    Finally, shop around. Do not just accept the first offer you get from the bank where you have your checking account. They might offer convenience, but they aren’t always the best deal. Use the comparison tools available online to see what the market is offering. A difference of 2% in your interest rate might not seem like much today, but over a five-year loan, it is the difference between a manageable payment and a stressful one.

    Check the fine print. Understand the terms. Know your limit. If you approach borrowing with a cold, analytical mindset rather than an emotional one, you will come out on top. Personal loans are a tool for movement, not a way to stand still. Use them to move forward. If you want to go deeper, Fast Loans California is a solid place to start.

    Quick answers

    What is the best personal loan in California?

    The best personal loan depends on your credit score and needs, but California residents should compare interest rates and terms between local credit unions and national online lenders.

    Which bank is the easiest to get a personal loan with?

    Online lenders and credit unions often have more flexible approval criteria compared to traditional big banks, making them easier to secure loans from.

    What is the easiest personal loan to get approved for?

    Loans from online lenders that specialize in bad credit or those with minimal documentation are typically the easiest to get approved for.

    How much would a $30,000 personal loan cost per month?

    A $30,000 loan might cost between $600 and $900 per month, depending on your interest rate and the repayment term length.

    Are there specific regulations for personal loans in California?

    Yes, California has strict usury laws and consumer protection regulations that limit the maximum interest rates lenders can charge.

  • The Real Cost of Debt in the Grand Canyon State

    Personal loans in Arizona

    Most financial advice tells you that personal loans are a trap designed to keep you underwater. That is a lazy take. A loan isn’t inherently a trap; it is a tool, and like any power tool, you can either build a deck with it or accidentally cut your thumb off. The problem isn’t the debt itself, but how much you pay to access it.

    In Arizona, we see a massive gap between people using credit to build a life and people using credit to survive a crisis. One group is using consolidation to escape high-interest credit card cycles, while the other is grabbing quick cash to cover an emergency repair. Both are using the same financial instrument, but their outcomes couldn’t be more different.

    If you are sitting in a coffee shop in Scottsdale or a kitchen in Mesa wondering if you should take out a loan, you aren’t just looking for money. You are looking for a way to move from point A to point B. Whether that is moving from $15,000 in credit card debt to a single manageable payment, or moving from a broken HVAC system to a repaired one, the math matters more than the marketing.

    We have seen enough people get burned by “easy” money to know that the devil is in the APR, not the lender. If you don’t know what you are signing, you aren’t borrowing; you are gambling. And the house always wins when you don’t know the rules of the game.

    Finding Your Way Through the Arizona Lending Maze

    The sheer number of lenders in the state can feel overwhelming. You have the massive national banks, the local credit unions that actually know your name, and the fintech companies that live entirely in your smartphone. Each one plays by a different set of rules regarding credit scores and collateral.

    If you have a solid history and a high credit score, you have the upper hand. You can walk into a local institution like the National Bank of Arizona and talk about unsecured loans. They offer amounts ranging from a $2,500 minimum up to a total of $100,000, which is helpful if you are looking at something significant like a home renovation or a major medical bill. These loans don’t require you to put your car or house up as collateral, which provides a layer of protection for your assets.

    However, the world isn’t always fair. Not everyone walks into a bank with a perfect score. If your credit is less than stellar, you might find yourself looking at different options. Some people think a bad credit score means they are completely locked out of traditional financing, but that isn’t necessarily true. You just have to look at where the risk-takers live.

    For instance, LendingPoint is often cited as one of the better options for those in the bad credit category. They provide loans between $1,000 and $36,500 with an APR that starts around 7.99%. It is a specialized niche, but it’s better than letting interest rates on unpaid bills spiral out of control while you wait for a “perfect” score that might never come. It is a temporary bridge, not a long-term lifestyle.

    Navigating these options requires a bit of legwork. You shouldn’t just take the first offer that hits your inbox. You need to compare the total cost of the loan over its entire lifespan. A low monthly payment is great, but if it takes you seven years to pay it off, you will end up paying for the loan twice. Does the monthly payment actually fit into your budget, or are you just delaying the inevitable?

    If you want to make this easier, there are ways to streamline the search. You can use tools like Acorn Finance to compare monthly payment options from several different lenders in a very short amount of time. It saves you from spending your Saturday morning filling out twenty different applications only to be rejected by nineteen of them. It’s a way to see what’s actually out there without the guesswork.

    The Real Math of Borrowing Money

    Let’s get into the weeds for a second. When you look at a loan offer, you are looking at three main numbers: the principal, the interest rate (APR), and the term. Most people focus on the principal, the amount they get in their bank account. That is a mistake. You need to focus on the APR and the term. That is where the real cost lives.

    Consider the difference between a short-term, high-interest loan and a long-term, low-interest loan. If you need $5,000 for an emergency, taking a loan with a 12% APR over three years is a very different financial commitment than taking a loan with 25% APR over twelve months. One feels like a manageable nudge; the other feels like a weight tied to your ankle.

    Here is a quick breakdown of how different lenders in our state typically structure their offerings:

    • Credit Unions: Often provide the lowest fixed rates and rarely charge application fees. They are great for people who want a predictable, stable payment.
    • National Banks: Good for large, unsecured amounts up to $100,000, especially if you already have a banking relationship with them.
    • Fintech/Online Lenders: Faster approval times and highly specialized for different credit tiers, but you have to watch the fine print on the APR.
    • Specialized Lenders: Companies like Oportun cater to different needs, offering smaller amounts for new customers, often between $500 and $4,500, while returning customers might see higher limits up to $8,000.

    We should also talk about the “secured” vs “unsecured” distinction. An unsecured loan is what most people mean when they say “personal loan.” You don’t have to hand over your car title. If you can’t pay, they can’t immediately seize your property, though they can still sue you or damage your credit. A secured loan, on the other hand, uses an asset as a guarantee. This makes the interest rate lower, but it puts your stuff on the line. It’s a trade-off between cost and risk.

    I remember a friend who tried to “save money” by taking a high-interest, short-term loan to pay off a credit card. He thought the immediate relief would be worth the interest. He was wrong. The interest on the personal loan ended up being higher than the credit card because he rushed into it without looking at the APR. He ended up in the same hole, just with a different name on the bill. Don’t be that person.

    Comparison of Loan Characteristics
    Lender Type Best For Typical Amount Range Common Benefit
    Credit Unions Debt Consolidation Variable Low, fixed rates
    National Banks Large Expenses $2,500 – $100,000 No collateral needed
    Online Lenders Quick Funding $1,000 – $36,500 Fast approval
    Niche Lenders Credit Building $500 – $8,000 Accessibility

    Avoiding the Debt Trap Pitfalls

    The biggest danger of a personal loan isn’t the money itself; it’s the false sense of security. When you consolidate five credit cards into one personal loan, your credit card balances go to zero. Suddenly, your debt looks much lower. You feel a sense of relief, a breath of fresh air. This is the most dangerous moment in your financial life.

    If you haven’t changed the habit that caused the credit card debt in the first place, you are going to end up with the personal loan and five new maxed-out credit cards in six months. We’ve seen this happen more times than we can count. The loan solves the symptom, but it doesn’t fix the disease. You have to treat the source of the spending, or you’re just moving numbers around on a spreadsheet.

    Another thing to watch for is the “prepayment penalty.” Some lenders want to make sure they get their interest, so they charge you a fee if you try to pay the loan off early. It sounds counterintuitive, why would a lender punish you for being responsible? But it’s a common tactic. Always ask: “If I get a bonus or a tax refund and want to pay this off tomorrow, what will it cost me?”

    You should also be wary of lenders that don’t clearly state their APR. If a lender only talks to you about “monthly payments” and avoids the term “APR” (Annual Percentage Rate), walk away. The APR is the only number that matters because it includes the interest rate plus any mandatory fees. It is the true cost of your money. If they won’t give it to you straight, they are hiding something in the fine print.

    Another way to find better deals is to use a service like LendWyse, which can connect you with up to 35 vetted lenders. This allows you to see a wide spectrum of rates, from as low as 7.99% APR, which helps you see if the offer you’re being pitched by your local bank is actually competitive or just what they think you’ll accept.

    It is also worth noting that your credit score is not a static thing. It is a living, breathing reflection of your reliability. Taking a loan to consolidate debt can actually improve your score over time because it lowers your “credit utilization ratio”—the amount of debt you have compared to your limits. But this only works if you keep those credit card balances at zero. If you use them again, your score will plummet faster than it went up.

    Making the Decision for Your Budget

    So, how do you know if a loan is “good” for you? It comes down to a very simple, unromantic calculation. Look at your monthly income. Look at your monthly mandatory expenses, rent, food, utilities, insurance. Subtract those from your income. What is left? That is your “margin.”

    If the new loan payment takes up more than 20% of your margin, you are playing with fire. You might be okay today, but one car repair or one unexpected medical bill will push you into a deficit. You need to build a buffer, not just a payment schedule. A loan should be a tool to create breathing room, not a tool that tightens the noose.

    If you are considering a loan for a major purchase, like a new kitchen or a solar installation, ask yourself if the interest rate on the loan is higher than the interest you could earn in a high-yield savings account or the value you expect to gain in the asset. If you are borrowing at 12% to install something that only increases your home value by 5%, you are losing money in real terms. It is a math problem, nothing more.

    Before you sign anything, get the paperwork in a physical or digital folder. Read the section on “Default.” What happens if you miss a payment? What is the late fee? What is the “default interest rate”? Some loans have a clause that says if you are even one day late, your interest rate jumps from 8% to 29%. That is a predatory trap, and you need to know if it’s lurking in your contract.

    At the end of the day, a personal loan is just a way to borrow time. You are trading a piece of your future income to solve a problem in your present. If the problem is worth the price of that time, then take the loan. If the price is too high, you’ll have to find another way to solve the problem, even if it’s a slower, harder way. Which is actually better: a slow path to financial stability or a fast path to deeper debt? There’s a useful breakdown over at arizonaziploan.com.

    Questions people ask

    What are the requirements for getting a personal loan in Arizona?

    Applicants typically need to be at least 18 years old, a resident of Arizona, and possess a valid ID, proof of income, and a bank account.

    Can I get a personal loan in Arizona with bad credit?

    Yes, many Arizona lenders offer unsecured personal loans for those with poor credit, though interest rates will likely be higher.

    How long does it take to receive a personal loan in Arizona?

    Approval can be instant, but funds are typically disbursed within one to five business days depending on the lender's processing time.

    Are there state-specific regulations for personal loans in Arizona?

    Yes, personal loans in Arizona are subject to the Arizona Consumer Credit Code, which regulates interest rates and lending practices.

    What is the maximum amount I can borrow with a personal loan in Arizona?

    Loan amounts vary by lender, but most provide anywhere from $1,000 to $50,000 based on your creditworthiness and income.

  • The Myth of the Perfect Loan Interest Rate

    Personal loan services and options

    Most people spend hours hunting for the lowest interest rate, but they’re often chasing a ghost. They obsess over a single decimal point while ignoring the hidden costs, the repayment terms, and the fine print that actually dictates whether a loan is a tool or a trap. A low rate means nothing if the fees or a rigid structure makes the monthly payment impossible to meet.

    The reality of modern lending is that “best” is subjective. What works for a high-earning professional with a pristine credit score will fail a freelancer with irregular income, even if their interest rates look identical on paper. Borrowing money is a mathematical calculation, but choosing a lender is a risk assessment of your own future cash flow.

    Lenders have moved far beyond the local bank branch. Today, the market is split between traditional giants and agile fintech players. You can find everything from small, quick-access funds to large, structured debt. Choosing the right one requires looking past the marketing and into the actual mechanics of the debt.

    The Mechanics of Modern Lending Options

    Personal loans work by providing a lump sum of cash that you pay back over a set period. This is different from a credit card, where interest accrues on revolving balances. With a personal loan, you know exactly when you will be debt-free. This predictability is why people often use them for debt consolidation or major home repairs.

    The market is currently divided into three main categories. First, there are the massive, established institutions like Wells Fargo. These lenders offer stability and the ability to manage your loan alongside your checking and savings accounts. They often have deep pockets but can be more rigid with their requirements.

    Second, you have specialized online lenders. Companies like SoFi and Upstart have changed how risk is assessed. Instead of just looking at a FICO score, some of these lenders look at your education, your employment history, or even your specific job title. This is a massive shift for people who have thin credit files but steady incomes.

    Third, there are the high-speed, high-cost lenders. These are for people who need cash immediately and might not meet the strict criteria of a traditional bank. They offer speed, but you pay for that convenience through higher rates. It is a trade-off of time versus money.

    When evaluating these options, keep these factors in mind:

    • Fixed vs. Variable Rates: Fixed rates stay the same; variable rates can move with the market.
    • Origination Fees: Some lenders take a cut of the loan before you even see it.
    • Prepayment Penalties: Check if you are charged a fee for paying the loan off early.
    • Loan Terms: This is the length of time you have to pay it back.

    It’s a balancing act. Too long a term, and you pay too much in interest. Too short a term, and your monthly bill might choke your budget. Understanding your own monthly “breathing room” is more important than finding the lowest APR.

    Decoding the Rate and Risk Relationship

    Interest rates are not just numbers; they are a reflection of how much a lender trusts you to pay them back. This is why credit scores remain the central pillar of the lending world. The higher your score, the lower the risk, and the lower the rate. If you fall into the “subprime” category, your options change significantly.

    Data suggests that the range of rates is wider than most realize. For example, Forbes Advisor notes that some of the best personal loans can start from as low as 6.49% APR. However, that rate is reserved for the absolute top tier of borrowers. Most people will land somewhere in the middle of the spectrum.

    Lenders use different math to decide your fate. Some use traditional scoring models. Others, like those mentioned by NerdWallet, compare rates across various providers to help users see where they fit. You can often check your rate with no impact to your credit score, which allows for a “soft pull” to see your options before you commit to a “hard pull” that stays on your report.

    If you need a specific amount for a specific purpose, you might consider a service like Jetzloan to see how different structures might affect your borrowing capacity. It is always better to shop around than to accept the first offer a bank sends your way.

    Consider this comparison of lender profiles:

    Lender Type Typical Credit Needed Speed of Funding Best For
    Traditional Bank High/Very High Slow (Days/Weeks) Existing Customers
    Online Fintech Moderate to High Fast (1-3 Days) Convenience & Tech
    Alternative Lender Low to Moderate Very Fast (Hours) Urgent Needs

    The math is cold. A 5% difference in APR might seem small over a month, but over five years, it can cost you thousands of dollars. Always calculate the total cost of the loan, not just the monthly payment.

    The Hidden Cost of Rapid Access

    Speed is the most seductive part of modern lending. We live in an age of instant gratification, and the financial sector has responded. Some lenders can move money into your account within hours. This is a lifesaver in an emergency, but it is also a predatory trap for the uneducated borrower.

    The more “convenient” a loan is, the more expensive it usually is. Lenders who specialize in quick approvals often have much higher thresholds for risk. To cover the cost of those defaults, they charge higher interest rates and more aggressive fees. It is a simple, brutal cycle of economics.

    You must watch out for the “origination fee.” This is a fee charged by the lender for processing the application and issuing the loan. It is often a percentage of the total loan amount. If you take out a $10,000 loan with a 5% origination fee, you only receive $9,500, but you still owe interest on the full $10,000. This effectively raises your APR significantly.

    Don’t forget the impact of the fine print. Some loans might offer a low rate for the first six months, only to see that rate jump once the introductory period ends. This is common in credit cards, but it can appear in specialized personal loan products as well. Always ask: “What is my rate at the end of this term?”

    Money has a cost. (Always remember that.)

    If you are using a loan to consolidate debt, the math must work in your favor. If you are moving a 24% APR credit card balance to a 12% APR personal loan, you are winning. But if the personal loan has high fees and a longer repayment term, you might actually end up paying more in total interest than you would have with the credit card. It is a common mistake that keeps people in a cycle of debt for years.

    Strategic Borrowing and Long-Term Stability

    A personal loan should be a tool for growth or a mechanism for efficiency, not a way to fund a lifestyle you cannot afford. Using a loan to consolidate high-interest debt is one of the most effective ways to improve your financial standing. It simplifies your monthly payments and lowers your total interest expense.

    Using a loan for home improvements can also be a sound move. If the interest rate on the loan is lower than the appreciation value of the home improvements, you are effectively building equity with borrowed money. This is a calculated use of leverage that can increase your net worth over time.

    However, the biggest risk is the “repayment vacuum.” This happens when a borrower uses a loan to pay off credit cards, feels a sense of relief because their credit card balances are now zero, and then starts spending on those same cards again. They end up with the personal loan debt and the new credit card debt. This is how financial ruin starts.

    To avoid this, you need a strict budget and a plan for the money you just “freed up.” If the loan saves you $200 a month in interest, you must ensure that $200 doesn’t simply vanish into lifestyle inflation. It should go toward your emergency fund or towards paying down the principal of the loan faster.

    To manage this effectively, follow these steps:

    • Calculate your “Debt-to-Income” ratio: Lenders look at this to see if you can handle more debt.
    • Set up autopay: Most lenders offer a small interest rate discount for automatic payments.
    • Avoid new debt: Do not take on new credit lines while paying off a large personal loan.
    • Review your terms: Read the contract to ensure there are no prepayment penalties.

    The goal is to use the loan to reach a specific destination, not to wander aimlessly through more debt. When you treat a loan as a scheduled event rather than a constant resource, you regain control of your finances.

    A personal loan is just a contract. It is a mathematical agreement that requires discipline to execute correctly. By understanding the difference between a low rate and a low total cost, and by distinguishing between a strategic tool and an expensive convenience, you can navigate the market without being consumed by it.

    A few things readers ask

    What are the different types of personal loan options available?

    Common options include unsecured personal loans, secured loans backed by assets, and fixed-rate or variable-rate loans tailored to different repayment needs.

    How do personal loan services determine my interest rate?

    Lenders base interest rates on your credit score, income level, debt-to-income ratio, and overall financial history.

    Can I use a personal loan for any purpose?

    Most personal loans are versatile and can be used for debt consolidation, home improvements, medical bills, or emergency expenses.

    What is the difference between a secured and an unsecured personal loan?

    Secured loans require collateral like a savings account or vehicle, while unsecured loans do not require assets but typically carry higher interest rates.

    Are there fees associated with personal loan services?

    Some lenders charge origination fees, application fees, or prepayment penalties, so it is important to review the loan agreement terms.

  • The Real Math Behind Navigating Arizona Personal Loans

    Personal loans in Arizona
    People often treat a personal loan like a magic wand for their bank account. It isn’t. It’s actually just a high-stakes math problem. If you use it to fund a lifestyle you can’t afford, you’re going to drown in interest. But if you use it strategically, to move debt around or cover a legitimate emergency, it can actually save your credit score.

    Here in Arizona, we see this all the time. It might be a sudden car repair in Phoenix or an attempt to consolidate credit card debt in Tucson. The urge to just “grab some cash” is strong. But not all cash is the same. The gap between a low-interest credit union loan and a predatory lender is often the difference between sleeping well and staring at the ceiling at 3:00 AM.

    We’ve looked closely at how different lenders handle the Arizona market. It isn’t just about how much you can borrow. It’s about the fine print people usually skip. You have to figure out if you’re walking into a trap or a genuine lifeline.

    Finding the Right Fit for Your Credit Profile

    Your credit score is the gatekeeper here. If yours is in the high 700s, you have leverage. You can shop around and demand better terms because you’re the one in control of the negotiation. For most people, though, it’s more complicated.

    If medical bills or a period of unemployment hit your credit, don’t assume you’re locked out. There are paths for people in that spot. For example, you can use a service like Acorn Finance to compare monthly payment options for personal loans in Arizona from various lenders in under two minutes. It’s a good way to stop guessing what you might actually qualify for.

    Your current score dictates your whole strategy. If you have “good” credit, look at unsecured loans from established institutions. They offer the most flexibility with amounts and rates.

    | Credit Category | Likely Loan Strategy | Primary Benefit |
    | :— | :— | :— |
    | Excellent (740+) | Traditional Banks / Large Credit Unions | Lowest APRs and highest limits |
    | Good (670-739) | Local Credit Unions | Competitive rates and personal service |
    | Fair (580-669) | Specialized Online Lenders | Higher approval odds for consolidation |
    | Poor (<580) | Secured Loans or Co-signers | Access to capital with higher costs | If your score is lower, your goal is rebuilding. Don't look for a massive lump sum for a boat. Look for a loan that simplifies your existing mess. An arizonaziploan.com search can help you see which lenders in the state care more about your actual income than just your FICO score.

    It’s a balancing act. You need enough to solve the problem without the monthly payment becoming a new crisis.

    The Unsecured Loan Advantage and Limits

    Unsecured loans are a specific breed of debt. You aren’t putting your house or car on the line. That’s why they’re popular for weddings or home renovations. Since there’s no collateral, the lender is taking a bigger personal risk on you.

    Because of that risk, they are stricter. You can’t just walk into a bank and demand $50,000 without a clear reason and a solid income history. However, the limits can be substantial if you qualify. For instance, the National Bank of Arizona offers unsecured loans that range from a $2,500 minimum up to a total of $100,000. That’s a lot of liquidity for someone trying to consolidate high-interest debt.

    I’ve seen people try to use these funds for “lifestyle creep.” They get a $10,000 loan to cover old debt, but then use the extra breathing room to buy more stuff. That’s a mistake. An unsecured loan should be a surgical tool. Use it to cut out bad debt, not to add more layers to it.

    If you go this route, watch out for fixed rates. Many lenders offer them, which is a blessing. Your payment stays the same every month, so there are no “variable rate” surprises when the economy shifts.

    Stability is everything.

    Look at the length of the term. A 36-month loan has a higher monthly payment than a 60-month loan, but you’ll pay much less in total interest. Do the math before you sign.

    Local Credit Unions vs. Big National Banks

    There is a real difference in the atmosphere when you walk into a local Arizona credit union versus a national powerhouse. It isn’t just about the decor; it’s about how they view your financial life.

    Local institutions often have more wiggle room because they are community-focused. For example, OneAZ Credit Union provides personal loans with competitive rates and flexible terms designed for things like emergencies or debt consolidation. They often look at your relationship with them, not just a computer screen.

    Credit unions are member-owned, meaning their goal isn’t to maximize shareholder profit. This often means lower fees and a more human approach. If you have a weird situation, like a recent job change or a one-time medical bill, a credit union is much more likely to listen to your explanation.

    The big banks are built for speed and scale. They have massive capital and automated systems that move money fast. If you have a perfect score and need a loan quickly, a big bank is hard to beat. They handle everything digitally without you ever needing to talk to a human.

    Consider these trade-offs:

    • Credit Unions: Lower fees, personal service, more flexibility with credit hiccups, slightly slower processing.
    • National Banks: Fast approval, massive limits, highly automated, less flexibility for “imperfect” applicants.
    • Online Lenders: Extreme speed, wide range of credit options, often higher rates, very impersonal.

    Don’t guess. Base your choice on what you actually need. If you need $5,000 to fix a radiator tomorrow, go with an online lender or a quick bank loan. If you need $40,000 to consolidate three years of credit card debt, you might want the personalized touch of a local credit union to make sure the plan is actually sustainable.

    The Reality of Interest Rates in 2026

    Rates move constantly. They shift with the economy, the Federal Reserve, and how much cash lenders have on hand. If you are looking at the market right now, be prepared for what “competitive” actually means.

    Some sources suggest you might see rates starting as low as 6.20% APR. That’s an incredible rate, but it’s usually reserved for people with near-perfect credit. For most people, the number will be higher. Look at the total cost of borrowing, not just the monthly payment.

    A low monthly payment can be a lie. If a lender offers a 72-month term to make the payment look small, they are essentially charging you a massive premium to pay them back slowly. You end up paying for that debt twice if you aren’t careful.

    When comparing options, use a tool like SuperMoney to discover the best personal loans in Arizona with clear terms. You need to see the APR, not just the interest rate. The APR includes the fees, and those fees can be a silent killer for your budget.

    Keep an eye out for the “fast approval” trap. We want the money now, but “fast” often means “expensive.” If a lender promises you cash in ten minutes without asking for any documentation, run. Real lending requires verification. If they aren’t asking for proof of income, they are likely making up for it with an interest rate that will haunt you for years.

    The math doesn’t lie, even if the marketing does.

    Quick answers

    What are the requirements for getting a personal loan in Arizona?

    Applicants typically need to be at least 18 years old, have a valid state ID, a steady income, and a bank account to receive funds.

    Can I get a personal loan in Arizona with bad credit?

    Yes, many Arizona lenders offer secured loans or specialized products for those with low credit scores, though interest rates will be higher.

    How long does it take to receive a personal loan in Arizona?

    Approval can be instant, while the actual transfer of funds typically takes between one to five business days depending on the lender.

    Are there any specific state regulations for personal loans in Arizona?

    Arizona follows standard consumer lending laws, and lenders must comply with state regulations regarding interest rate caps and disclosure requirements.

    What is the difference between a bank loan and a credit union loan in Arizona?

    Banks often offer faster processing and larger amounts, while Arizona credit unions frequently provide lower interest rates and more personalized service.

  • Oltre la comodità: la verità su PaySaveCardCasinoIT e il mondo delle prepagate

    Recensioni di PaySaveCardCasinoIT

    Pensare che un casinò sia “buono” solo perché ha un sacco di slot è una sciocchezza. Molti giocatori perdono un sacco di tempo su piattaforme che hanno giochi bellissimi, ma sistemi di pagamento che sembrano rimasti agli anni ’90 o, peggio, che ti mettono i bastoni tra le ruote quando devi prelevare i tuoi soldi.

    Il vero problema del gioco d’azzardo online non è la grafica delle slot, ma come viene gestito il flusso di cassa. Se ricaricare il conto è un calvario, l’intera esperienza ne risente, anche se il software della slot machine è coloratissimo.

    Abbiamo passato le ultime settimane a guardare i dati e quello che scrive la gente su PaySaveCardCasinoIT. Non siamo qui per fare pubblicità: vogliamo capire se questa soluzione per i pagamenti sia davvero utile per giocare con serenità o se ci sia sotto qualcosa di più complicato.

    Il mercato si sta spostando verso la privacy. La gente non ha più voglia di inserire i dati della carta di credito principale su un sito che, per quanto sia regolamentato, resta un bersaglio per il phishing.

    Il meccanismo delle prepagate e il nodo della licenza ADM

    Andiamo al sodo. Quando si parla di casinò online che accettano Paysafecard in Italia, la questione non è solo la velocità, ma la legalità. C’è molta confusione tra i siti che operano nel “grigio” e quelli che hanno la benedizione dell’Agenzia delle Dogane e dei Monopoli.

    Usare una carta prepagata ti dà un cuscinetto di sicurezza. La compri in negozio, carichi l’importo che vuoi e la usi. Non c’è alcun legame diretto tra il tuo conto in banca e il sito di gioco. Per chi vuole tenere sotto controllo le spese, questo è un vantaggio enorme.

    Il processo di ricarica è quasi meccanico: entri nel conto gioco, scegli l’opzione dedicata e inserisci il codice a 16 cifre della scheda. Non devi comunicare i tuoi dati personali durante la transazione, un bel sollievo per la privacy. Paysafecard casino è un tipo di casinò che ti consente di effettuare depositi tramite la Paysafe card, e il tutto è molto rapido.

    Però occhio: non tutti i casinò sono uguali. Un operatore serio deve avere la licenza ADM. Senza questo marchio, anche se il pagamento è veloce, potresti lottare con una burocrazia infinita per recuperare le vincite. Gli operatori che abbiamo controllato più da vicino sono tutti in regola, quindi i fondi sono protetti dalle leggi italiane.

    Il vantaggio è chiaro, ma il rischio c’è sempre se non controlli l’operatore. La velocità è tutto.

    Caratteristica Paysafecard Standard Bonifico Bancario Carta di Credito
    Privacy Massima (Nessun dato bancario) Bassa (Dati visibili) Media
    Velocità Deposito Immediata 1-3 giorni Immediata
    Velocità Prelievo Moderata Lenta Variabile
    Commissioni Spesso presenti al carico Nulle/Basse Variabili

    Analisi delle recensioni: cosa dice davvero la gente

    Spesso ci si fida della pubblicità o dei primi risultati su Google, ma la verità sta nei forum o nei siti di recensioni indipendenti. Se vuoi un parere onesto, devi andare dove la gente scrive quando è arrabbiata o quando è davvero contenta.

    Il caso di PaySaveCardCasinoIT è interessante perché sta a metà tra un servizio di pagamento e l’esperienza di gioco. Molti utenti scrivono su piattaforme esterne. Leggi le recensioni dei servizi di PaySaveCardCasinoIT su Trustpilot per capire se il supporto clienti risponde in tempo o se ci sono lamentele sui limiti di prelievo.

    Abbiamo notato un fatto: chi usa le prepagate si lamenta meno della sicurezza, ma è molto esigente sulla velocità con cui il saldo viene aggiornato. Se il sistema di ricarica ci mette anche solo dieci minuti, il giocatore perde la concentrazione o la voglia di giocare. La pazienza, nel gioco d’azzardo, è poca.

    C’è chi dice che il servizio sia perfetto e chi si lamenta delle commissioni nascoste quando si compra la carta nei negozi. Bisogna essere consapevoli che la comodità ha un costo. Non è un errore del casinò, è il prezzo per non usare la carta di credito.

    È davvero tutto così semplice? Forse no.

    Le opinioni sono divise. Da un lato c’è chi cerca la velocità, dall’altro chi cerca la protezione. Spesso queste due cose non vanno d’accordo. Chi vuole la privacy estrema accetta di pagare un po’ di più per non collegare la propria banca.

    Le recensioni dicono che la trasparenza è l’unica cosa che conta. Un casinò che nasconde le regole sui massimali di prelievo tramite Paysafecard non durerà molto in Italia, soprattutto con le leggi attuali sulla trasparenza.

    Parametri tecnici: massimali, commissioni e tempi

    Entriamo nei dettagli tecnici, quelli che le brochure ignorano. Analizzando un casinò online, non basta sapere che accetta Paysafecard. Devi sapere *come* lo fa. Ci sono differenze enormi tra gli operatori che abbiamo analizzato.

    I massimali sono il primo scoglio. Se vuoi fare una sessione di gioco seria, potresti trovare limiti di deposito giornalieri troppo bassi con le prepagate. Spesso è un limite del fornitore del pagamento e non del casinò, ma è un’informazione che devi avere prima di iniziare.

    Le commissioni sono un altro punto. Caricare una Paysafecard al tabaccaio o al supermercato costa un po’ di più rispetto a un bonifico. Se lo fai spesso, la cifra si fa sentire. È il prezzo che paghi per la tranquillità.

    Il prelievo, invece, è il vero banco di prova. Anche se i depositi sono istantanei, il prelievo verso una prepagata può richiedere più tempo per la verifica. Il sistema deve essere sicuro che la carta usata per il prelievo sia la stessa usata per giocare, e questo controllo può sembrare una seccatura burocratica.

    Ecco cosa valutare prima di depositare:

    • Massimali di deposito: controlla il limite minimo (spesso 10-20 euro) e quello massimo giornaliero.
    • Commissioni di acquisto: guarda quanto costa di più comprare la carta nei punti vendita fisici.
    • Tempi di elaborazione: distingui tra il tempo di approvazione del casinò e quello della transazione bancaria.
    • Disponibilità bonus: controlla se puoi usare le prepagate per i bonus (molti casinò le escludono).

    Molti casinò, per evitare frodi, limitano l’uso delle prepagate per i prelievi, chiedendo metodi più tracciabili come il bonifico. Molti giocatori lo scoprono solo quando deve incassare la vincita. È un errore comune.

    Strategie per una gestione sicura del budget

    Non si può parlare di casinò senza parlare di gestione del rischio. Il gioco deve essere un divertimento, non un modo per cercare di recuperare soldi che non hai. Le prepagate sono, in realtà, ottimi strumenti per moderarsi.

    Il vantaggio psicologico è reale. Se carichi una carta da 50 euro, sai che non andrai oltre. Non rischi di finire sul conto corrente principale a fine serata. È una barriera mentale molto forte.

    Però c’è un rischio: la tentazione di ricaricare subito una nuova carta dopo aver perso. Il fatto che sia facile comprare una carta al bar rende tutto troppo semplice. Questo è il lato oscuro della comodità digitale.

    Per muoversi in sicurezza, ecco qualche consiglio pratico:

    1. Definisci un budget mensile fisso e non sforare mai.
    2. Usa solo casinò con licenza ADM per stare tranquillo sui pagamenti.
    3. Leggi sempre i termini dei bonus prima di attivarli.
    4. Controlla spesso l’estratto conto delle tue prepagate per evitare addebiti strani.

    Il controllo deve essere totale. Non farti dettare i ritmi dal sistema. Se un casinò è velocissimo a prendere i tuoi soldi ma lento a restituire i profitti, cambia operatore subito.

    In definitiva, usare metodi come Paysafecard è un’evoluzione necessaria per la privacy, ma serve disciplina. La tecnologia è un’arma a doppio taglio: può essere un alleato per la sicurezza o il tuo peggior nemico se non sai come gestirla.

    Domande frequenti

    Posso giocare a slot con deposito 10 euro su PaySaveCardCasinoIT?

    Sì, è possibile effettuare ricariche contenute, come un deposito da 10 euro, per accedere alle slot machine disponibili.

  • Itcasino Mastercart: realtà operativa o solo un’altra promessa digitale?

    Recensioni di Itcasino Mastercart

    Ti stai chiedendo se Itcasino Mastercart sia un metodo sicuro per gestire i tuoi prelievi o solo un altro miraggio digitale in un mercato già saturo? La risposta non è semplice. Dipende tutto da quanto sai distinguere un operatore serio da un clone creato per attirare traffico facile.

    Il mondo del gioco d’azzardo online in Italia è un campo minato. Da un lato ci sono gli operatori con licenza ADM, dall’altro un mare di piattaforme che usano nomi simili a quelli famosi per confondere l’utente. Itcasino Mastercart si muove proprio su questo confine sottile, cercando di posizionarsi come un ponte tra i metodi di pagamento tradizionali e la velocità richiesta dai giocatori moderni.

    Molti utenti cercano questa specifica combinazione di nome e metodo perché vogliono usare le proprie carte, come la Mastercard, per spostare fondi rapidamente. Tuttavia, la confusione è tanta. Ci sono siti che promettono protezione totale dei vincite attraverso transazioni specifiche, ma la realtà è che la sicurezza dipende sempre dalla licenza che il sito possiede, non solo dal metodo che usi per depositare.

    Non lasciarti incantare dai nomi accattivanti. La vera domanda da farsi è: dove finiscono i miei soldi se il sito non ha una licenza italiana valida? Il rischio di finire su siti “clone” oggi è altissimo.

    La trappola dei nomi simili e la sicurezza reale

    Il termine “Itcasino Mastercart” è diventato un punto di discussione frequente nelle community di giocatori. Perché proprio questo nome? Perché unisce l’idea di un casinò italiano con la praticità della carta Mastercard. Questo meccanismo di branding è spesso studiato per intercettare chi cerca soluzioni veloci per il proprio cash-out.

    Il problema sorge quando queste piattaforme non sono veri casinò, ma semplici interfacce che reindirizzano i tuoi soldi verso altri canali. Alcuni report indicano che il marchio si concentra molto sulla protezione dei vincite tramite metodi di transazione specifici. Ma attenzione: la protezione della transazione non è la stessa cosa che la protezione del tuo saldo totale.

    Se un sito si presenta con un nome che sembra un mix tra un metodo di pagamento e un portale di gioco, sospetta subito. I siti seri sono chiari. Non giocano con la tua confusione digitale. Se ti trovi davanti a una piattaforma che sembra un “campo di battaglia” tra chi vuole facilitare i flussi di cassa e chi vuole solo cavalcare l’onda della confusione, stai perdendo tempo (e forse anche altro).

    Prima di versare anche solo dieci euro, controlla sempre la licenza. Se il sito non è elencato nei portali ufficiali di verifica, sei già fuori dai margini di sicurezza. La velocità di pagamento è importante, ma la certezza del pagamento lo è di più.

    Cosa guardare per non bruciarti i soldi

    Quando decidi di iscriverti a un casinò che accetta metodi come Mastercard o altre carte prepagate, ci sono dei parametri tecnici che non puoi ignorare. Non basta che il tasto “deposita” funzioni bene. Devi guardare sotto la superficie.

    Ecco una lista di elementi fondamentali da verificare prima di inserire i dati della tua carta:

    • Limiti di deposito e prelievo: Alcuni siti ti permettono di depositare 500 euro ma ne accettano solo 50 in prelievo al giorno. È un trucco comune per trattenere i tuoi fondi il più a lungo possibile.
    • Commissioni nascoste: Controlla se l’operatore applica costi extra quando usi carte Mastercard o prepagate. Spesso dicono che è “gratis”, ma poi riducono il valore del tuo bonus per compensare.
    • Tempi di elaborazione: Un sito serio non dovrebbe impiegare settimane per un prelievo standard. Se vedi tempi vaghi, scappa.
    • Licenza ADM o internazionale riconosciuta: Se non è italiana, sappi che in caso di contestazione legale avrai pochissime speranze.

    Io ho visto persone perdere la pazienza con siti che promettono la velocità della luce ma poi bloccano i prelievi con scuse burocratiche infinite. Se vuoi evitare questi mal di testa, leggi le recensioni su piattaforme indipendenti. Ad esempio, puoi trovare informazioni molto dettagliate sulla velocità di pagamento e sulle percentuali reali su siti specializzati come Eurobet Casino, che offre dati concreti sulla velocità di payout e sulle percentuali di pagamento, come un 97.87% per certi servizi.

    La trasparenza è tutto. Se un sito ti nasconde i termini e le condizioni dietro un muro di testo illeggibile, non è un casinò, è un labirinto. Un operatore affidabile ti dice chiaramente quanto tempo ci metterà a rivedere i tuoi soldi sul conto.

    Verifica sempre le recensioni degli altri utenti su siti come it.trustpilot.com/review/itcasinomastercart.xyz prima di procedere.

    Confronto tra operatori e metodi di pagamento

    Non tutti i casinò sono uguali, specialmente per quanto riguarda la gestione delle carte di credito e debito. C’è una differenza enorme tra un operatore consolidato e uno emergente che cerca di rubarti l’attenzione nel 2026.

    Prendiamo come esempio la differenza tra un gigante del settore e una nuova piattaforma che punta tutto sulla Mastercard. Il primo ha una struttura finanziaria che garantisce il pagamento anche se perdi milioni; il secondo potrebbe chiudere le porte domani mattina se ha avuto una settimana negativa. La stabilità è la tua prima linea di difesa.

    Caratteristica Operatore AAMS (Consolidato) Nuovi Operatori / Clone
    Sicurezza Licenza Massima (ADM/Regolamentato) Incertezza totale
    Velocità Payout 1-5 giorni (o meno) Indefinita / Bloccata
    Metodi Accettati PayPal, Mastercard, Postepay Spesso solo crypto o carte dubbie
    Affidabilità Alta Molto bassa

    Se utilizzi carte prepagate come le Postepay, la situazione è ancora più delicata. Molti nuovi casinò online del 2026 stanno cercando di accettare questi metodi perché sanno che sono i preferiti da chi vuole mantenere un certo distacco tra il conto principale e il gioco. Tuttavia, l’uso di carte prepagate non ti protegge se il sito non è regolamentato. È un errore comune pensare che la protezione della carta equivalga alla sicurezza del casinò.

    La verità è che i metodi di pagamento sono solo strumenti. Se il motore è rotto, non importa se hai le gomme migliori del mondo. Se il sito è un clone, i tuoi soldi spariranno comunque.

    Il rischio dei siti clone e la confusione digitale

    Perché ci sono così tanti siti che cercano di imitare i nomi dei servizi finanziari o di altri casinò famosi? La risposta è il traffico organico. Se un utente cerca “Itcasino Mastercart”, il proprietario di un sito clone spera che finisca proprio sul suo portale invece che su quello del concorrente serio. È una guerra di parole chiave.

    Questa proliferazione di siti specchio è un problema serio. Alcuni report descrivono proprio questa crisi d’identità del brand ItCasino MasterCart, dove l’obiettivo è confondere il giocatore sulla natura reale del sito. Non è una teoria del complotto; è una strategia di marketing aggressiva e spesso illegale che mira a chi non sa navigare con attenzione nel web.

    Molti di questi siti promettono di “proteggere i tuoi vincite” tramite transazioni criptate o metodi specifici, ma si tratta spesso di una copertura per rendere più difficile il tracciamento dei fondi da parte delle autorità. Se il sito non ti permette di comunicare facilmente con un supporto clienti umano e professionale, sei nel pericolo. Un bot che risponde dopo tre ore non è un servizio clienti, è un muro di gomma.

    Non farti trascinare nel caos. Se un sito ti sembra troppo bello per essere vero, o se il nome ti suona troppo “strano” e un po’ troppo generico, probabilmente lo è. La semplicità è spesso sinonimo di onestà nel mondo dei casinò. Se devono spiegarti con un trattato di filosofia come funziona un prelievo, c’è qualcosa che non va.

    Controlla sempre la licenza sul fondo della pagina. Se non vedi il logo dell’autorità competente (come l’ADM in Italia), chiudi tutto immediatamente.

  • The Mechanics of Debt Consolidation and the Reality of Personal Loans

    Personal loan and debt consolidation services

    Forty-four lenders. That’s the number of institutions analysts looked at to figure out which ones actually offer the best terms for anyone trying to clean up their finances. The testing was pretty straightforward: they looked at interest rates and loan terms, since those are the only things that really change how much you end up paying back.

    Debt consolidation isn’t magic, though. It’s just math. You take out one big personal loan to wipe out several smaller, high-interest debts. Once those balances are at zero, you’re left with just one monthly payment, hopefully at a lower interest rate than the weighted average of what you were paying before.

    It can make a messy financial life feel a lot more organized. Instead of juggling five different due dates and random interest rates for a handful of credit cards, you deal with one fixed amount. That makes budgeting easier and helps you avoid late fees. But it only works if the terms on the new loan are actually better than the old ones.

    A lot of people get stuck in a loop of minimum payments. When credit card rates go up, the principal balance barely moves no matter how much you pay. A personal loan breaks that cycle. By swapping revolving credit card debt for a structured installment loan, you actually have a definitive end date for your debt.

    The Requirements for Securing Competitive Terms

    Lenders don’t just give out low interest rates to anyone. They’re looking at specific metrics to gauge their own risk. The big one is your FICO score. If you want the best rates on the market, you generally need a score of 670 or higher. It’s essentially a shorthand for how well you’ve handled money in the past.

    Then there’s your income. Lenders need to see that you have enough cash left over after your living expenses to cover the new payment. They use your debt-to-income ratio, or DTI, to figure this out. A DTI below 36% is usually the sweet spot. If your debt eats up too much of your paycheck, you’ll likely face higher rates or even a denial.

    You can still get approved even if your score isn’t perfect. Some online lenders, like Avant or Upstart, offer products for people who don’t fit the strict mold of big traditional banks. These options are great if you need a way forward, but they often come with higher interest rates to cover the lender’s risk. You have to decide if the immediate help is worth the higher APR.

    If your credit score is low, you have two moves: apply now and take the higher rate, or wait and fix the score. Small things, like staying current on all accounts or lowering your credit utilization, can move a score a lot in just a few months. Waiting usually pays off in the long run because you’ll save so much on interest.

    Here is how different borrower profiles usually look:

    Profile Type Typical Credit Score Likely Outcome
    Prime Borrower 720+ Lowest interest rates, longest terms
    Near-Prime 670 – 719 Competitive rates, standard terms
    Subprime 600 – 669 Higher rates, shorter terms, or specialized lenders

    Comparing Loan Structures and Speed of Funding

    Not all personal loans are the same. Some lenders prioritize speed, while others focus on how much they can lend you. For example, OneMain Financial can get you funded as quickly as one hour after you close the loan. That’s a huge deal if you’re dealing with an urgent bill or a financial crisis.

    On the other hand, Discover® personal loans focus on keeping things transparent. They offer competitive rates and fast funding without the hidden fees some lenders tuck away in the fine print. When you’re shopping around, don’t just look at the monthly payment. Check the total cost, including origination fees and any penalties for paying the loan off early.

    The amount you can borrow changes too. Some lenders cap out at low amounts, while others allow for much larger sums. You can find providers offering up to $30,000 for debt consolidation, which is usually plenty to clear several high-interest cards. If you want to see what’s out there before you commit, you can use a service like Jetzloan to explore your options.

    You really need to understand the difference between fixed and variable rates. Most consolidation loans use fixed rates, meaning your payment stays the same until the loan is paid off. That’s the stability most people want. Variable rates are much riskier; if the economy shifts, your monthly payment could go up unexpectedly.

    Common ways people use these loans include:

    • Credit Card Consolidation: Moving high-interest revolving debt to a lower-rate installment loan.
    • Medical Bills: Managing large, unexpected hospital expenses.
    • Home Improvement: Funding repairs that increase your property value.
    • Emergency Expenses: Covering sudden costs like car repairs.

    The logic is simple: you’re using a tool to solve a problem. But using a loan to pay for a wedding or a vacation is a mistake. Consolidation works best when you’re targeting high-interest debt that you can’t manage with your current monthly cash flow.

    The Risk of the Debt Trap Cycle

    The biggest danger isn’t the loan itself; it’s the borrower’s behavior. People often consolidate their credit cards into a loan, which leaves the cards with zero balances. It feels like the debt is gone, but it’s just moved from one place to another.

    If you start using those empty cards again, you’ll end up with a massive loan payment plus new credit card debt. That’s how a quick fix turns into a disaster. It’s a common trap, and you need serious discipline to avoid it. You have to treat those original cards as if they’re closed, even if they’re still open.

    Lenders will check your debt-to-income ratio (DTI) to make sure you aren’t overextending yourself. If you’re already at your limit, a new loan might feel like a relief, but it actually makes you more vulnerable. If your income drops or an emergency hits, you’ve traded several small, flexible minimum payments for one large, mandatory one.

    Think about these things before you move forward:

    • Total Interest Paid: Compare the total interest on the loan versus your current cards.
    • Monthly Cash Flow: Does the new payment actually free up money, or is it just a different due date?
    • Discipline Level: Do you have a real plan to stop using the cards you just paid off?

    Be honest about why you’re doing this. If the debt came from a one-time emergency, a loan is a solution. If it’s from spending more than you earn every month, a loan is just a temporary mask. One solves the problem; the other just delays it.

    Evaluating Lenders for Your Specific Needs

    As you start looking, you’ll see that lenders cater to different people. Some are for the “perfect” borrower, offering the lowest rates and most flexible terms. These are usually the big banks or top-rated online lenders. They want the lowest risk, so they demand the highest credit scores.

    Then there are specialized lenders. These companies often move much faster and look at more than just a FICO score, they might check your bank history or job stability instead. They are easier to get through, but you have to read the fine print. That speed and ease usually comes with a higher interest rate.

    Keep an eye on your credit score during the process. Most lenders do a “hard pull” when you apply, which can cause a small, temporary dip in your score. It’s normal, but it matters if you’re planning to apply for a mortgage or a car loan in the next few months.

    The “best” loan is simply the one that keeps your total cost down and stays within your monthly budget. There isn’t one perfect lender, only the one that fits your situation right now. Taking the time to compare different offers is the only way to make sure you aren’t overpaying just to make your life a little simpler.

    You might wonder: “Won’t I just end up with more debt once my credit cards are empty?” That depends on you. A loan consolidates what you already owe, but it doesn’t stop you from spending more. Only a change in how you spend can do that.

    Good to know

    Can I get a personal loan for debt consolidation with no credit check?

    While some lenders offer specialized products, most reputable personal loans for debt consolidation require a credit check to determine eligibility and interest rates.

    How can I find a personal loan for debt consolidation with low interest rates?

    To secure the lowest rates, compare offers from multiple banks and credit unions, and aim to improve your credit score before applying.

    What are the benefits of using Discover for debt consolidation?

    Discover offers personal loans that can simplify multiple payments into one monthly installment, helping you manage debt more effectively.

    Are there guaranteed debt consolidation loans for bad credit?

    No legitimate lender can guarantee approval, but certain lenders specialize in working with individuals with poor credit, often at higher interest rates.

    Which banks offer debt consolidation loans and is U.S. Bank a good option?

    Major banks like U.S. Bank, Wells Fargo, and Chase offer consolidation loans; U.S. Bank provides structured personal loans designed to help manage and combine existing debt.